Mortgage Applications Fall as 30-Year Rate Hits 7.35%
MBA reports drop in purchase and refinance applications for week ending November 13, as U.S. mortgage rates climb
By AmeriNews Newsroom ·
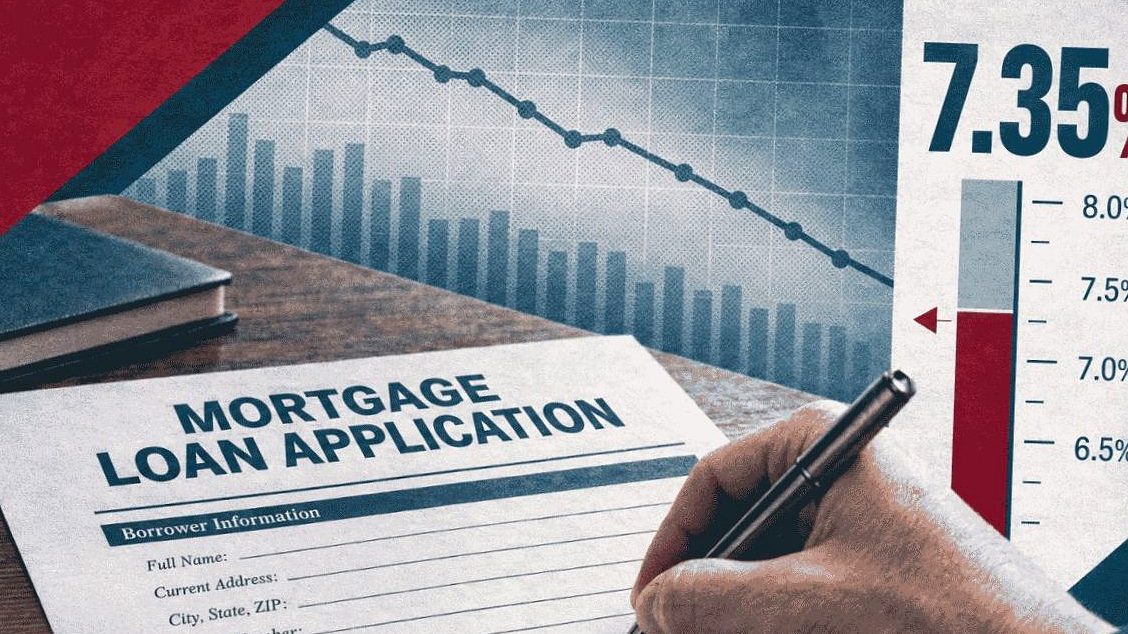
Mortgage applications in the United States fell again during the week ending November 13, 2026, a period in which the 30-year fixed rate rose to 7.35%. The data come from the Mortgage Bankers Association's (MBA) Weekly Mortgage Applications Survey, which also showed purchase applications 18% lower than the same period a year ago and a refinance index 54% below the level recorded a year earlier.
On a seasonally adjusted basis, total application volume fell 2.3% from the previous week; on an unadjusted basis, it dropped 5%. The Refinance Index decreased 2% from the previous week, while the seasonally adjusted Purchase Index fell 3% and the unadjusted Purchase Index was down 7% compared with the previous week.
Higher rates pressure buyers
Joel Kan, MBA's Vice President and Deputy Chief Economist, said in a statement that Treasury yields rose last week amid data showing accelerating inflation in October and signals from Federal Reserve officials that further rate hikes may be needed in the coming months. According to Kan, mortgage applications declined as mortgage rates climbed, with the 30-year fixed rate reaching its highest level in three weeks at 7.35%. Kan added that purchase applications were down 18% from a year ago, as affordability challenges tied to elevated rates continue to push potential buyers out of the market.
Regarding refinancing, Kan noted that overall activity fell for the week, but Federal Housing Administration (FHA) refinances rose nearly 7%, helped by a rate roughly 30 basis points below the conventional rate.
Share by product type
The refinance share of total applications rose to 41.1%, up from 39.8% the previous week, while the adjustable-rate mortgage (ARM) share fell to 10.8%. Among loan types, the FHA share of total applications increased to 16.1% from 15.5%; the Department of Veterans Affairs (VA) loan share rose 40 basis points to 12.8%; and the U.S. Department of Agriculture (USDA) share held steady at 0.5%.
The average rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) rose to 7.35% from 7.21%, while the rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased 10 basis points to 7.31%. The average rate for 30-year fixed-rate FHA-backed mortgages rose 8 basis points to 7.06%, while the rate for 15-year fixed-rate mortgages held steady at 6.64%. The average rate for 5/1 ARMs rose to 6.38% from 6.28%.
Xactus index points to further slowdown
Xactus's Mortgage Intent Index, which tracks aggregated and anonymized credit inquiry data from its platform, fell week over week to 95.7, a change of -2.94%. Thomas Lloyd, Xactus's Chief Strategy Officer, said movement in mortgage rates and the Veterans Day holiday may have contributed to the decline. According to Lloyd, the daily index, launched on November 2, posted its lowest weekly reading on Thursday, November 12, at 94.5, before rebounding to 95.7 on Friday, November 13. He noted that between Tuesday and Thursday, mortgage rates rose while mortgage intent fell roughly 8.6% over the same period.
Lloyd said the size of the decline may point to factors beyond rate movement alone, citing possible productivity and workflow disruptions tied to instability in Microsoft's email service. He also noted that even with Friday's rebound, the weekly index remains about 27% below the same period last year, which he said underscores persistently weak borrower demand.
This week's set of indicators reinforces a familiar pattern in the U.S. housing market: with 30-year rates above 7%, the affordability barrier remains the chief drag on demand, more so than any short-term supply fluctuations. The sharp year-over-year drop in refinancing, combined with purchase applications still well below year-ago levels, suggests the sector's recovery will likely remain gradual unless rates ease consistently.